Two paths. One clean slate.
Most people qualify for one of two chapters. Here’s the plain-English difference — and we’ll confirm which fits you on a free call.
7Chapter 7 — Fresh Start
A full discharge of unsecured debt. Most cases are complete in about four months, and most clients keep everything they own thanks to California’s exemptions.
- Erases credit cards, medical bills, personal loans, old utilities
- Creditor calls and lawsuits stop the day we file
- Typically 3–4 months start to finish
- Income-qualified (the "means test") — we check in minutes
13Chapter 13 — Catch-Up Plan
A court-approved repayment plan over 3–5 years that stops foreclosure and repossession, lets you catch up on what you’re behind, and often pays back pennies on the dollar to everyone else.
- Stops foreclosure sales and repossessions immediately
- Catch up missed mortgage or car payments over time
- Can strip second mortgages and reduce car loans
- Works even if you earn too much for Chapter 7
The myth: you lose everything. The truth: most clients keep it all.
California’s exemption laws are among the most generous in the country. Here’s what is protected in a typical case.
Three steps to a clean slate.
Free consultation
Call, click, or come in. In 30 minutes you’ll know which chapter fits, what you keep, and what it costs.
We prepare & file
You send us a short checklist of documents; we do the rest. The day we file, every creditor must stop.
Discharge & rebuild
One short meeting with the trustee (we’re with you), then your discharge — and a credit-rebuilding plan to go with it.
Flat fees. No surprises. Payment plans that fit.
You’ll know the full cost before you commit — and most clients pay less than one month of the minimum payments they’re about to stop making.
Free Consultation
A real attorney reviews your situation and tells you which chapter fits, what you keep, and what it costs. No pressure.
Chapter 7
Flat attorney fee. Payment plans available before filing. Fee waivers for the court cost if you qualify.
Chapter 13
Most of the attorney fee is paid through your court-approved plan — so you can file quickly to stop a foreclosure.
Sale date this week? Garnishment starting Friday? We can stop it today.
An emergency "skeleton" filing can be on the court’s docket within hours. The moment it is, the automatic stay takes effect and creditors must stop — by federal law.
- Foreclosure sale scheduled
- Wage garnishment about to start
- Vehicle repossession threatened
- Bank account levied or frozen
- Court date on a creditor lawsuit
- Utility shut-off notice
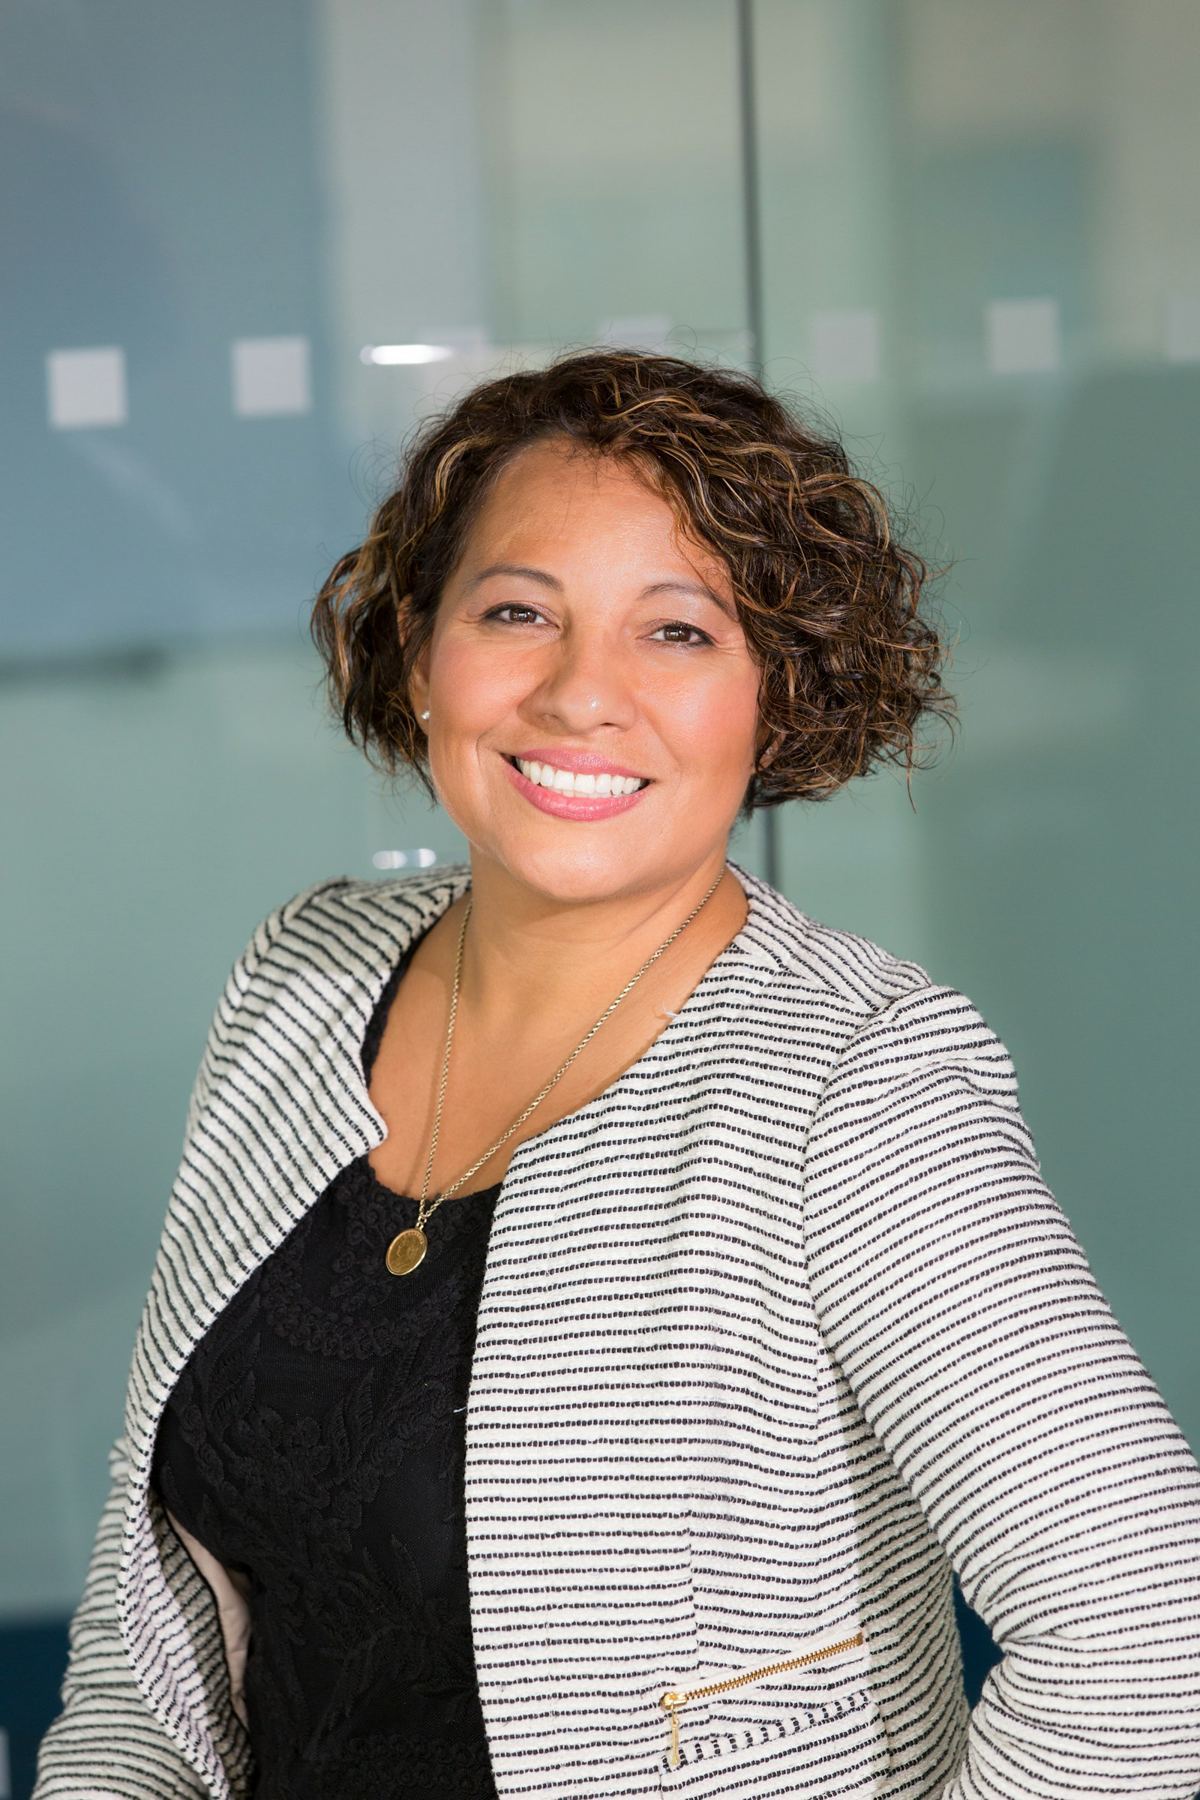
The attorney you meet is the attorney who handles your case.
Jordan Reyes has filed more than 2,400 Chapter 7 and Chapter 13 cases in the Central District of California — and personally handles every one. No paralegal hand-offs, no call center.
“Nobody plans to end up here. My job is to make the way out simple, fast, and free of judgment.”
- 20+ years exclusively in consumer bankruptcy
- Member, National Association of Consumer Bankruptcy Attorneys
- Former Chapter 7 trustee staff attorney — knows how cases are reviewed
- Evening, weekend, and video appointments
Straight answers.
Will I lose my house or my car?
Almost never. California exemptions protect a large amount of home equity, your vehicle, and retirement accounts. If you’re behind on payments, Chapter 13 lets you catch up while you keep the property.
How fast do the creditor calls stop?
The same day we file. The automatic stay is federal law — creditors who keep calling can be sanctioned by the court.
How much does it cost, and can I make payments?
Flat fees, quoted up front at your free consultation. Chapter 7 fees can be paid in installments before filing; most Chapter 13 fees are paid through your plan.
Will bankruptcy ruin my credit forever?
No. Most clients see their scores rise within 12–18 months because their debt-to-income ratio resets. Many qualify for a car loan within a year and a mortgage in 2–4 years.
Do I have to go to court?
Usually just one short meeting with the trustee, often by phone or video. We attend with you and prepare you for every question.
Does my spouse have to file too?
Not necessarily. We’ll look at whose name the debt is in and recommend the approach that protects your household best.
Find out in one call whether you qualify — and what you get to keep.
No cost. No obligation. No judgment.
(800) 555-0142